How to Negotiate a Cash Settlement With a Car Insurer
You get a better settlement by challenging the valuation with your own evidence, not by asking for more money.
Free to compare
A lowball offer on a five-year-old sedan
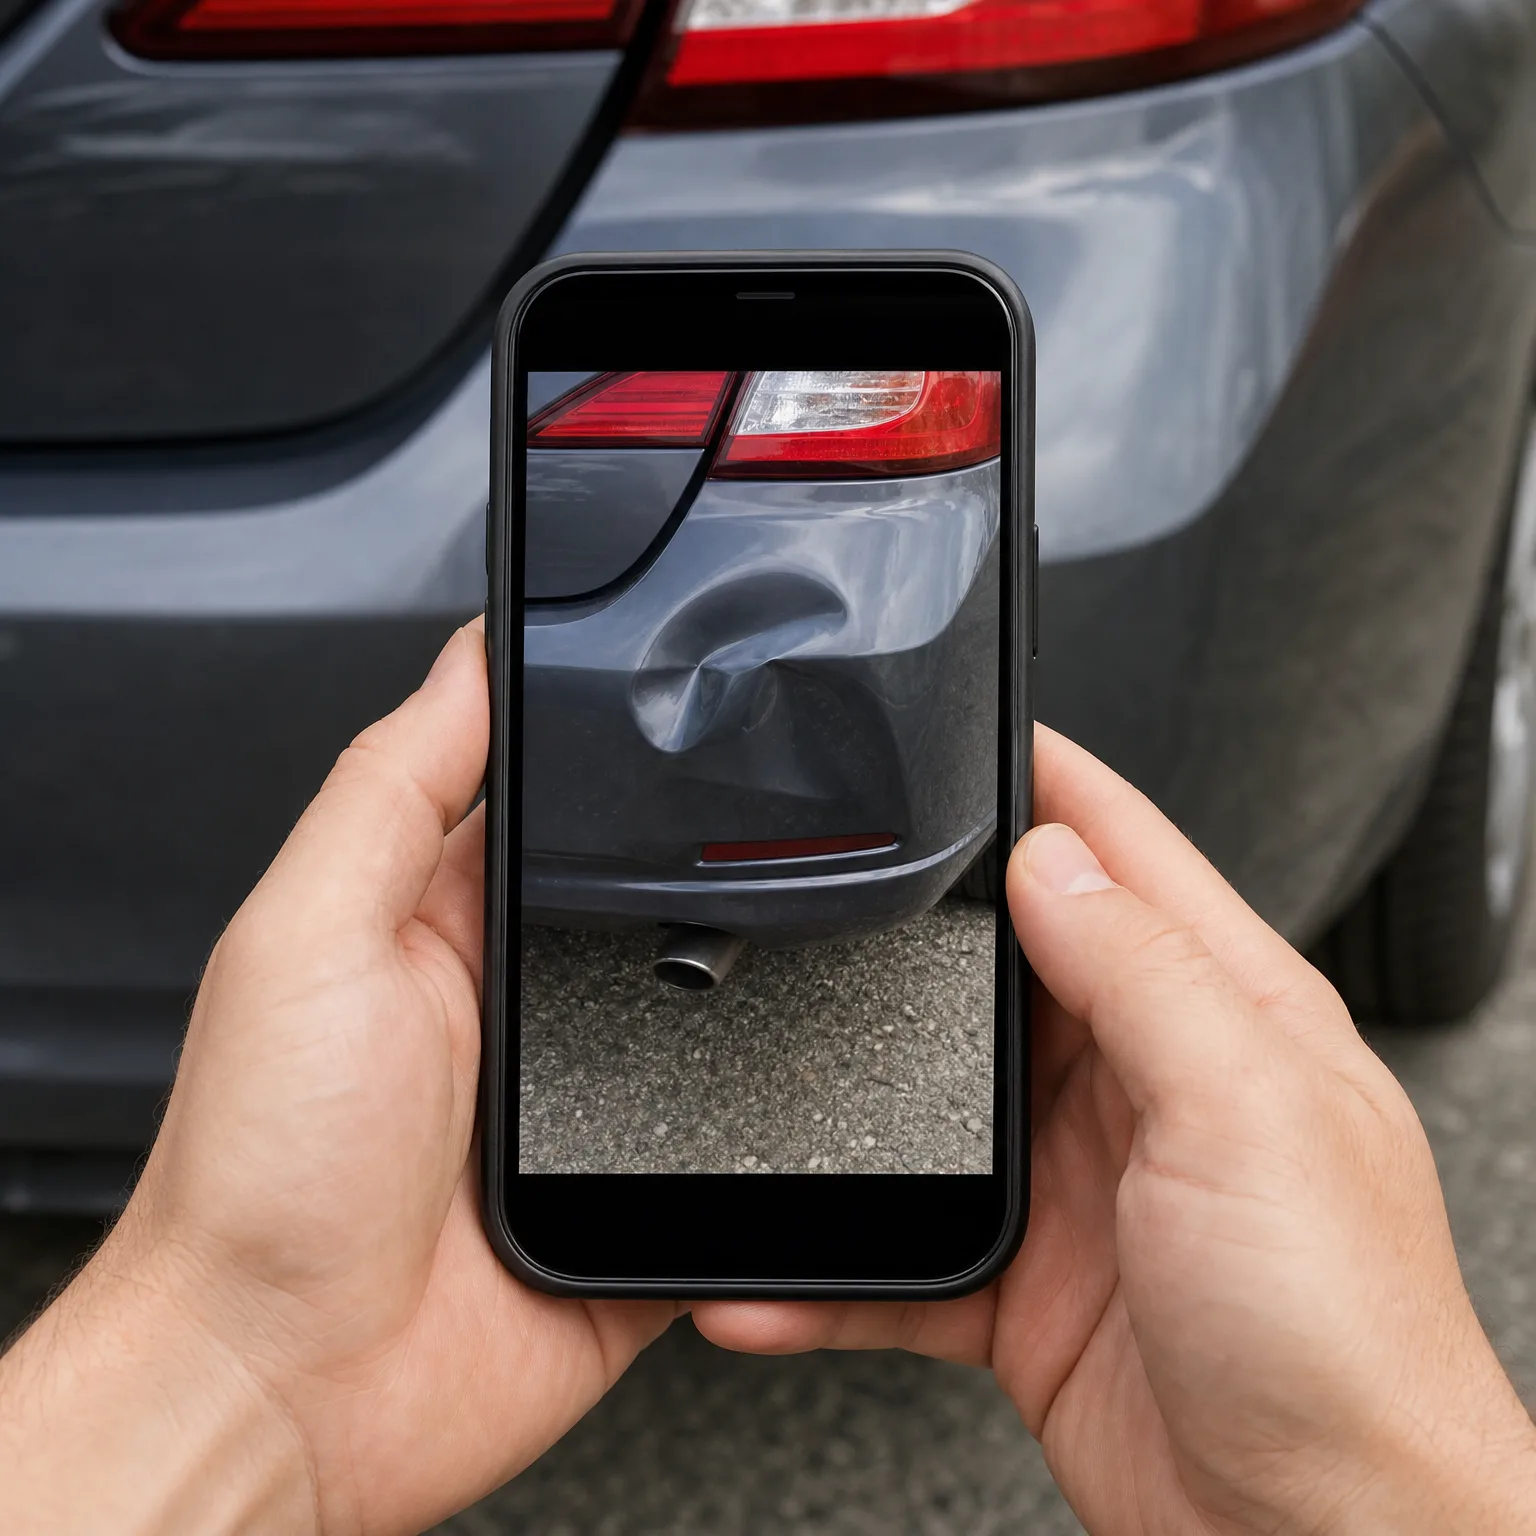
A driver's car was totaled after a collision that wasn't their fault. The insurer's first offer came in low, based on a valuation report that listed the car as having higher mileage and rougher condition than it actually had, and that used comparable listings from used car lots an hour away in a cheaper market. The driver almost accepted it, since the number looked official and the report came with charts.
Instead they pulled their own comparables, four listings for the same make, model, and trim within a short drive, all with similar mileage, all priced higher than the insurer's figure. They also sent photos and service records showing recent tires and a new battery. They wrote a short letter stating the corrected value and attached the evidence. The adjuster came back with a revised offer close to the driver's number within a week. Nothing about the claim changed except the paperwork backing it up.
What if the insurer won't move at all?
Some adjusters hold firm even with strong comparables, especially if their internal valuation tool is treated as final by company policy. When that happens, ask specifically what their appeals process is, since most insurers have one even if it isn't mentioned upfront. Put your request in writing and reference your state's claims handling rules, which often require insurers to justify a valuation with evidence, not just assert it.
If that stalls, you can invoke the appraisal clause in your policy, which forces a neutral third party to set the value. You can also file a complaint with your state's insurance department, which sometimes prompts a second look. These steps take longer, but they exist because insurers expect some claims to be pushed back on.
Once you know how to push for a fair settlement, compare quotes to make sure your next policy backs you up just as well.
What actually moves a settlement number
- Your own comparables Find three or four similar cars for sale near you, same model, year, and mileage range. These carry more weight than a generic valuation report.
- Maintenance records New tires, recent repairs, or low mileage for the car's age all raise its value. Send receipts and service history, not just a description.
- The valuation report itself Read it line by line and flag errors in mileage, options, or condition. Even small mistakes compound into a lower number.
- A clear counteroffer in writing State your number and back it with evidence rather than just disputing theirs. Written requests create a record and are harder to brush off.
- Your policy's appraisal clause Check if your policy lets you demand an independent appraisal when you disagree. This is a formal backstop, not just a negotiating tactic.
Why insurers start low and how pushing back changes that
Insurers settle total loss claims using valuation software that pulls from listings and auction data, then applies adjustments for mileage, condition, and options. These tools are built to be defensible on average, not accurate for your specific car. They often pull comparables from a wider radius than necessary or apply generic condition assumptions, which skews the number down more often than up.
Adjusters are trained to work within that number unless you give them a reason not to. A reason means documentation, not a strong feeling that the car was worth more. When you bring better comparables or point out factual errors in the report, you're not asking for a favor, you're correcting an input the system got wrong. That's why specific, written pushback works far better than a phone call expressing frustration.
This plays out differently depending on your state and your insurer. Some states require insurers to use specific valuation methods or respond to disputes within a set process, so check your state's rules on claims handling. Some insurers have a more flexible internal appeals step than others, and some policies include an appraisal clause that isn't always mentioned unless you ask.
Where this doesn't work as well is when the car was already in poor condition, had prior damage, or sits in a thin market where few comparables exist. In those cases there's less room to move, no matter how well-documented your counteroffer is. Knowing which situation you're in helps you calibrate how hard to push and when a settlement offer is actually close to fair.
The first offer is a starting number from a formula, not a verdict on what your car was worth.