How to Negotiate With an Insurance Adjuster on a Total Loss
You negotiate a total loss by challenging the valuation with your own evidence, not by arguing over the number itself.
Free to compare
The valuation is a starting offer, not a verdict
When an insurer declares your car a total loss, they send a valuation report built from comparable listings nearby. That report is produced quickly and often leans on comparables that are higher mileage, lower trim, or farther away than what you actually had. It is a starting point, built to be reasonable enough that most people accept it without question.
Negotiating works because the valuation is an estimate, not a fact, and estimates can be wrong in specific, provable ways. If you can show the adjuster that the comparables they used don't match your car, or that better comparables exist, you are not asking for a favor. You are correcting an input to their own formula, which is a request they're set up to handle.
Where this gets harder is when your state or insurer uses a fixed third-party valuation tool rather than letting the adjuster set the number directly. In that case your negotiation is really with the tool's data, and you push back by submitting better comparables for the adjuster to enter, rather than arguing a number with the adjuster personally.
It also matters whether you owe money on the car. If you have a loan, the lender gets paid first from the settlement, and any negotiation affects what's left for you, not just the headline number. Knowing that before you start keeps you focused on the number that actually matters to you.
What actually moves the number
- Pull your own comparables Find three or four similar cars for sale nearby, matching year, mileage, and trim. Send them to the adjuster as evidence the valuation missed better matches.
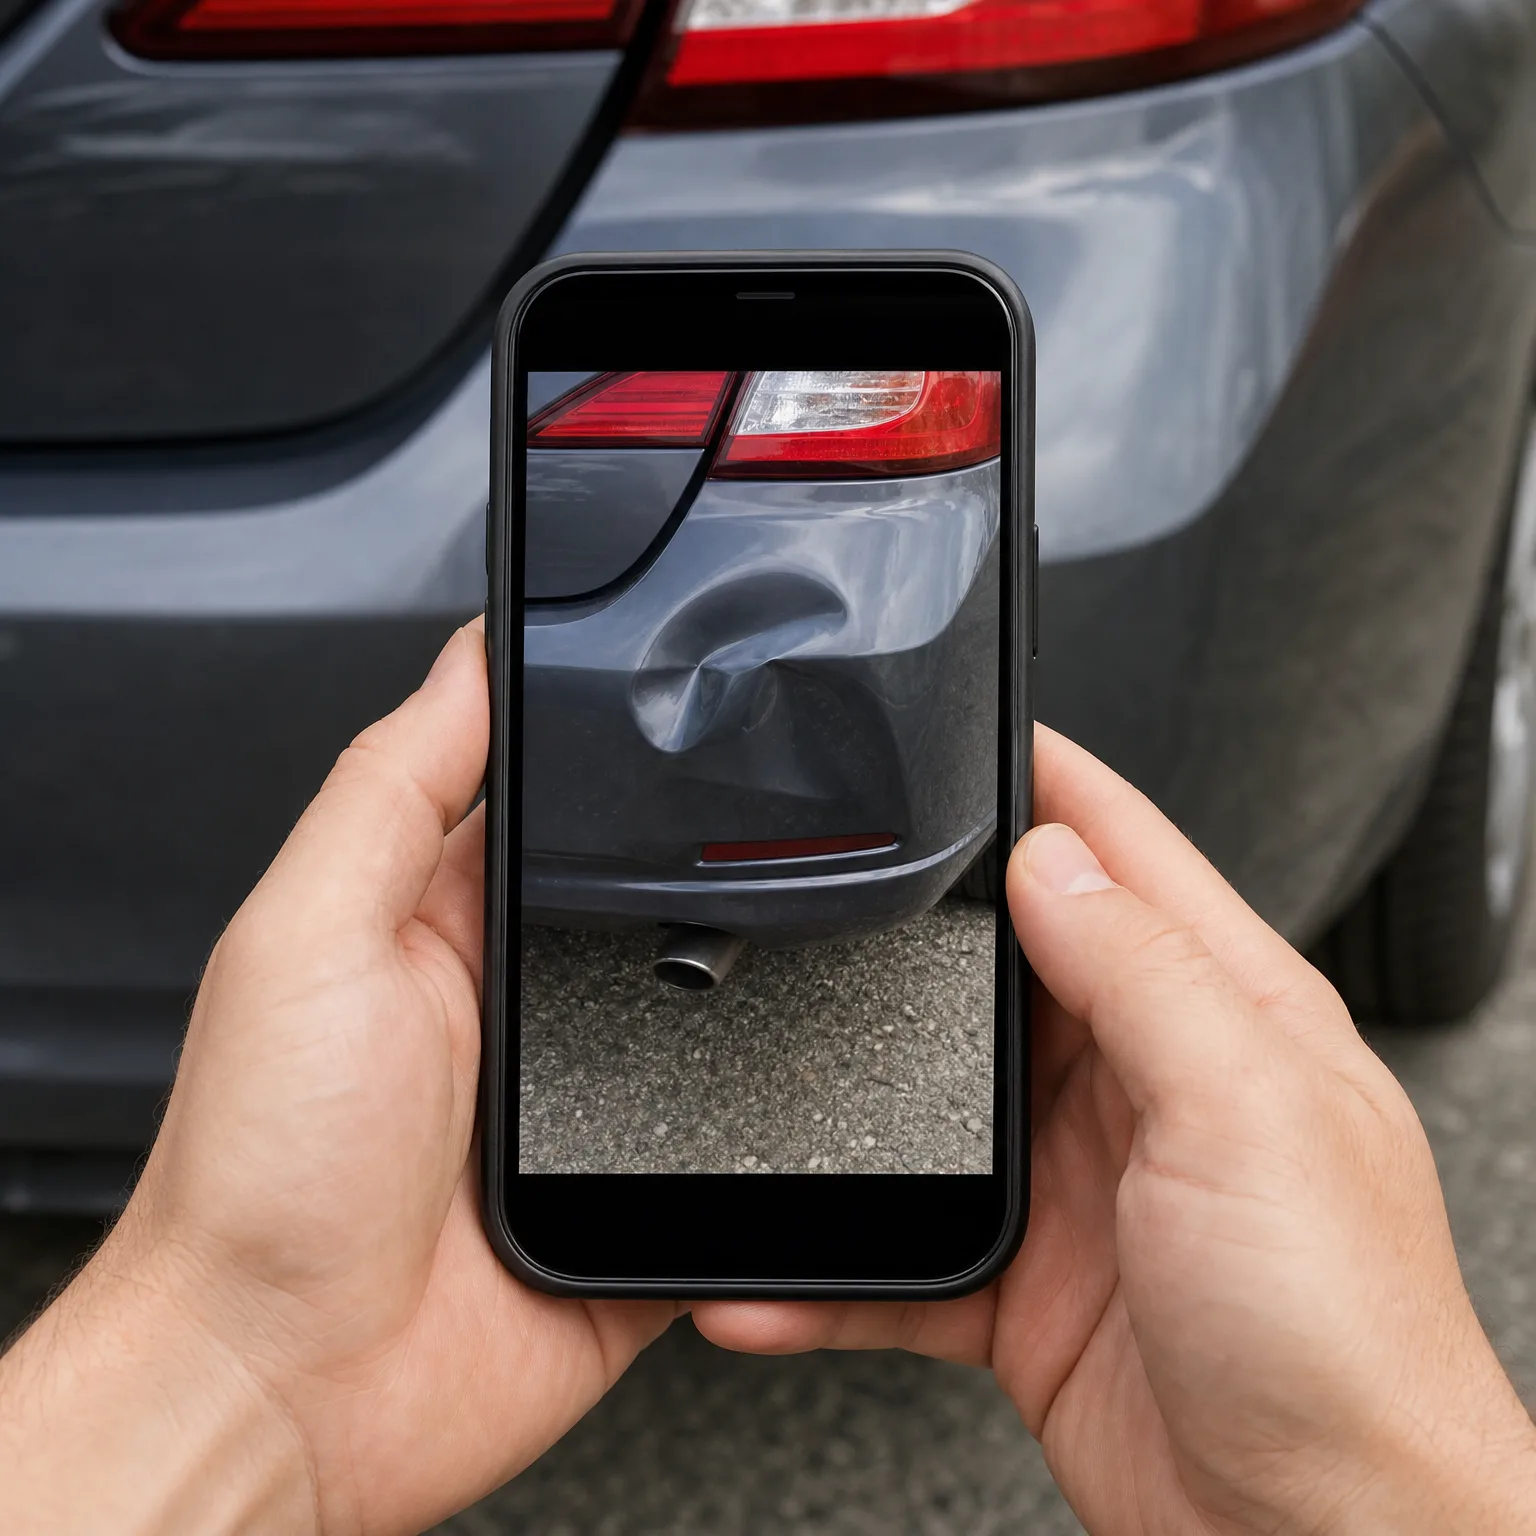
- Document condition and options List upgrades, recent repairs, and extras the valuation may have missed. Photos and receipts make these claims concrete instead of just asserted.
- Get the valuation report itself Ask for the full report, not just the final number. Reviewing it line by line often reveals a weak comparable you can directly challenge.
- Know your state's rules Some states require specific valuation methods or allow independent appraisals. Check what your state allows before you assume the first offer is final.
- Put your counter in writing A written counteroffer with evidence attached carries more weight than a phone call. It also creates a record if you need to escalate later.
Once your total loss is settled, compare quotes to replace the coverage on your next car.
Whether you push back on the first offer
If you do
You ask for the valuation report, submit your own comparables, and send a written counteroffer. The adjuster reviews it and often raises the number, especially if your comparables are genuinely stronger. It takes more time, usually a week or two, but the settlement reflects your actual car.
If you don't
You accept the first number to move on quickly. In many cases that number is reasonable, but if the comparables were weak or mismatched, you've left money on the table with no way to go back for it once the check clears and the claim closes.
A mismatched comparable costs someone real money
Someone's five-year-old sedan was totaled in a rear-end collision that wasn't their fault. The insurer's valuation report used three comparables, two of which were a lower trim level without the leather interior and navigation package their car actually had. The third comparable was from a dealer listing two states away, priced lower than local market rates.
They spent an evening searching local listings and found four comparable cars, same trim, similar mileage, all priced noticeably higher than the insurer's number. They sent these along with photos of their car's interior and a receipt for a recent tire replacement, then submitted a written counteroffer explaining the mismatch. The adjuster came back within a week with a revised offer that split the difference, still short of the counter but meaningfully higher than the original. They accepted, because the new number reflected the car they actually owned rather than a cheaper version of it.
Can I get an independent appraisal if I disagree with the adjuster?
Often yes, depending on your policy and state. Many policies include an appraisal clause letting you hire your own appraiser if you and the insurer can't agree, with a third appraiser breaking a tie if needed. Check your policy wording for this clause and confirm whether your state requires insurers to honor it. If it exists, it's a formal backstop when negotiation alone stalls.
What happens to my loan if the settlement is less than I owe?
You remain responsible for the difference unless you have gap coverage. If the payout doesn't cover the loan balance, the lender still expects full payment, and that gap becomes money you owe out of pocket. Check your loan agreement and policy for gap coverage before assuming the settlement closes out the loan. This is worth confirming early, since it changes how hard you push on the valuation itself.
How long do I have to accept or dispute the settlement offer?
It depends on your state and insurer, so check your policy and any letter they send for a specific deadline. Some states set outer limits on how long insurers can take to settle, but your own window to respond is usually shorter and stated in writing. If you need more time to gather comparables, ask for an extension rather than letting a deadline pass by default.